
Financial markets can be classified in many ways. One useful way is by the type of intermediary that stands between buyers and sellers. At first glance, this may seem like a technical detail. In practice, it has a big effect on how easily an asset can be traded, how much trading costs, and how prices are set.
There are two basic types of intermediary: brokers and dealers. Markets where brokers bring buyers and sellers together are called broker markets. Markets where dealers buy and sell from their own inventory are called dealer markets.
Both types still exist because each has advantages. Real estate is a broker market. The foreign exchange and corporate bond markets are dealer markets. Stock markets have features of both.
This article explains how brokers and dealers work, compares the two types of market, and looks at over-the-counter (OTC) markets, where dealers play a central role.
What is a Broker?
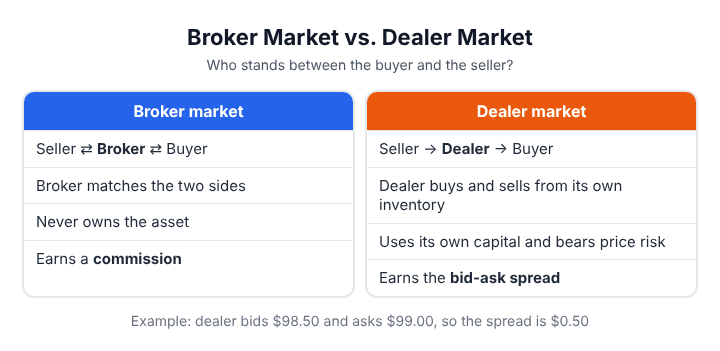
A broker is an agent. The broker’s job is to bring buyers and sellers together and arrange the trade. The broker earns a commission, which may be a percentage of the deal or a fixed fee.
A broker never owns the asset being traded. So the broker does not need to invest its own capital in inventory or take the risk that prices will fall.
Because brokers need little capital, the barriers to entry are low, and competition is intense. This is why brokerage charges have fallen sharply. Many discount brokers now charge a flat fee per trade, and some charge no commission at all on simple stock trades, earning money in other ways. One controversial method is payment for order flow: the broker sends its clients’ orders to large market-making firms, such as Citadel Securities or Virtu, which pay the broker a small amount per share. The practice is banned in the UK and is being phased out in the EU.
What is a Dealer?
A dealer is a principal. The dealer buys assets for its own account and sells them from its own inventory. To the seller, the dealer is the buyer. To the buyer, the dealer is the seller.
This means the dealer must:
- Use its own capital to hold an inventory of assets
- Bear the loss if prices fall before it can sell
- Have a wide network to find buyers and sellers quickly
Because dealers take more risk, they do not earn a commission. Instead, they earn the spread.
How the Bid-Ask Spread Works
A dealer quotes two prices:
- Bid price: The price at which the dealer will buy.
- Ask (offer) price: The price at which the dealer will sell.
The difference is the spread. For example, a bond dealer quotes a bid of $98.50 and an ask of $99.00. If the dealer buys a bond from one client at $98.50 and sells it to another at $99.00, it earns $0.50.
Spreads reflect risk. If an asset is volatile or rarely traded, the dealer may hold it longer and risk a bigger loss, so it quotes a wider spread. For heavily traded assets, competition among dealers keeps spreads very narrow.
Being a dealer requires large capital and a broad network, so this role is usually played by banks and large financial firms.
Measuring the Cost of Trading
The spread is a cost to anyone who buys and later sells. Traders measure it in three ways.
- The quoted spread is simply the ask minus the bid. In the bond example above, it is $99.00 − $98.50 = $0.50.
- The percentage spread makes costs comparable across assets with different prices:
Percentage spread = (Ask − Bid) ÷ Midpoint price × 100
The midpoint is ($99.00 + $98.50) ÷ 2 = $98.75, so the percentage spread is $0.50 ÷ $98.75 × 100 = about 0.51%. A large company’s shares might trade at a spread of a few hundredths of a percent, while a rarely traded bond can cost several times more. - Market impact matters for large orders. Dealers quote prices for a limited size. An order bigger than that pushes the average price paid above the quoted ask, or the average price received below the bid.
Broker Markets vs. Dealer Markets
| Basis | Broker Market | Dealer Market |
|---|---|---|
| Role of intermediary | Agent: matches buyers and sellers | Principal: trades from own inventory |
| Ownership of asset | Never owns the asset | Owns the asset until resold |
| Earnings | Commission or fee | Bid-ask spread |
| Capital required | Low | High |
| Risk borne | Low | High (price and inventory risk) |
| Speed of execution | Depends on finding a counterparty | Immediate, if the dealer is quoting |
| Best suited to | Assets with many buyers and sellers | Assets with fewer participants |
| Examples | Real estate, stock exchange order books | Forex, corporate bonds, Nasdaq market makers |
Where Do Stock Exchanges Fit?
Older textbooks describe the New York Stock Exchange (NYSE) as a broker market and Nasdaq as a dealer market. The reality is more nuanced.
- The NYSE is best described as an auction market. Buy and sell orders meet in a central order book, and today most of this matching is done electronically and continuously, which is why such markets are also called order-driven markets. Designated market makers on the floor also trade for their own account to keep trading orderly, so they act partly as dealers.
- Nasdaq was built as a network of competing dealers, called market makers, who quoted bid and ask prices. Today it also matches orders electronically.
Both exchanges now rely heavily on electronic trading, so the old distinction has narrowed.
Advantages and Disadvantages of Dealer Markets
The main advantage of a dealer market is immediacy. A seller does not have to wait for a buyer. The dealer buys at once and takes on the task of finding the next buyer.
However, dealer markets have drawbacks:
- Cost: Spreads can be higher than broker commissions, especially for less liquid assets.
- Liquidity can vanish in a crisis: When prices fall rapidly, dealers stop buying and try to sell what they hold. This happened in 2008, when trading in many bonds and mortgage securities dried up.
- Information advantage: Dealers see a large flow of orders and know more than ordinary investors. Some may use this to trade for their own profit rather than to provide liquidity.
In general, assets with many active traders are traded in broker or auction markets, because counterparties are easy to find. Assets with few participants are traded in dealer markets, because someone must stand ready to buy and sell.
Over-the-Counter (OTC) Markets
An over-the-counter market is a decentralized market where trades are agreed directly between two parties rather than on an exchange. Dealers play a central role, quoting prices to clients. Brokers may also help to find counterparties.
OTC markets are not physical places. Trades are arranged by phone and, increasingly, on electronic platforms.
Large volumes of bonds, foreign exchange and derivatives such as interest rate swaps trade OTC. Smaller company shares and many unlisted securities also trade this way. Retail investors rarely see these markets, but they are vital to the global financial system.
Exchange Trading vs. OTC Trading
On an exchange, trades are cleared through a clearing house, also called a central counterparty (CCP). After the trade, the CCP becomes the buyer to every seller and the seller to every buyer, so neither party is exposed to the other’s default. In a traditional OTC trade, each party takes the risk that the other will fail to pay.
| Feature | Exchange Trading | OTC Trading |
|---|---|---|
| Structure | Centralized | Decentralized |
| Contracts | Standardized | Can be customized |
| Price transparency | High: prices are public | Lower: prices may not be published |
| Counterparty risk | Managed by a central counterparty | Borne by the parties (unless centrally cleared) |
| Regulation | Heavily regulated | Lighter, though tightened since 2009 |
| Typical users | Retail and institutional investors | Mainly institutions |
Risks of OTC Markets
- Lack of information: Prices may not be published, so price discovery is difficult. Different parties may pay very different prices for the same security. Exchange safeguards such as circuit breakers do not apply.
- Counterparty (credit) risk: If one party goes bankrupt, it may not honor its contracts. Because institutions are linked through many contracts, one failure can spread to others, as in the 2008 crisis.
- Liquidity risk: For some instruments, it can be hard to find a counterparty quickly, especially in stressed markets.
After the 2008 crisis, G20 leaders agreed in 2009 that standardized OTC derivatives should be cleared through central counterparties and reported to trade repositories. This has made a large part of the OTC derivatives market safer and more transparent.
Frequently Asked Questions
What is the main difference between a broker and a dealer?
A broker acts as an agent and earns a commission without owning the asset. A dealer acts as a principal, buys and sells from its own inventory, and earns the bid-ask spread.
Is the stock market a broker or a dealer market?
It has features of both. Most major exchanges match orders in an electronic order book, but market makers also trade for their own account to provide liquidity.
Why are bonds mostly traded in dealer markets?
There are thousands of different bonds, and many trade rarely. Dealers stand ready to buy and sell, which makes trading possible when matching buyers and sellers would take too long.
Are OTC markets risky?
They can be riskier than exchanges because of lower transparency and counterparty risk. Post-2009 reforms have reduced these risks for standardized derivatives.