
Few words have moved global markets as sharply as “taper.” In May 2013, a hint from the US Federal Reserve that it might slow its bond buying sent bond yields higher and emerging market currencies lower within weeks. The episode became known as the “taper tantrum,” and it showed how much the world had come to rely on cheap money from the Fed.
What Does QE Tapering Mean?
Quantitative easing (QE) means a central bank creates new money, in the form of bank reserves, and uses it to buy assets such as government bonds and mortgage-backed securities. These purchases inject money into the financial system and push long-term interest rates down. Central banks usually turn to QE when their main policy rate is already close to zero and the economy still needs more support.
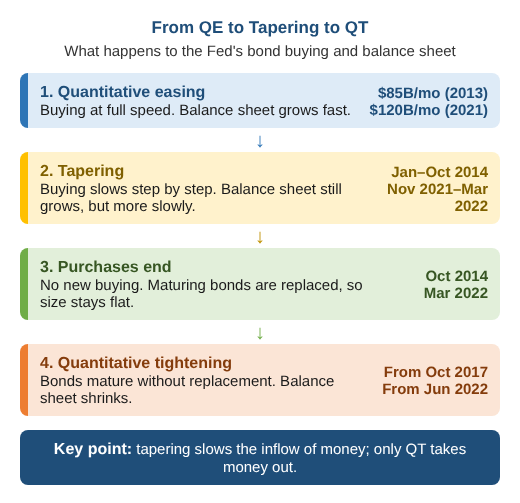
Quantitative easing tapering is the gradual slowing of those asset purchases. The central bank keeps buying, but each month it buys a little less, until the purchases stop completely. Tapering is a way of winding down QE gently, without shocking markets.
A simple analogy helps. Think of the central bank’s balance sheet as a bathtub. QE is the tap running at full force, tapering is turning the tap down step by step, and ending purchases is turning the tap off. Through all of tapering, water is still flowing into the tub, so the balance sheet keeps growing, only more slowly.
For example, under its third round of QE (QE3), the Fed was buying $85 billion of assets a month in 2013: $45 billion of Treasury bonds and $40 billion of mortgage-backed securities. Cutting that to $75 billion a month, which the Fed did from January 2014, was tapering. Note that QE is run by the central bank, which is independent of the government, not by the government itself.
Tapering Is Not the Same as Quantitative Tightening
Tapering is often described as “the reverse of QE,” but that is not quite right. During a taper, the central bank is still adding money to the system, just at a slower rate. The true reverse of QE is quantitative tightening (QT), where the central bank lets bonds mature without replacing them, so its balance sheet shrinks and reserves are drained.
The Fed made this sequence very clear after the pandemic. It tapered from November 2021 to March 2022, raised interest rates from March 2022, and began QT in June 2022. The Fed slowed the pace of QT in 2024 and 2025 and announced an end to the runoff in late 2025.
A Short History of Fed Tapering
The 2013 Taper Tantrum
On May 22, 2013, Fed Chair Ben Bernanke told Congress that the Fed could slow its purchases in the coming meetings if the economy kept improving. Markets reacted at once. The 10-year US Treasury yield rose from about 1.6% in early May 2013 to nearly 3% by September 2013, even though the Fed had not yet bought a single dollar less.
Emerging markets were hit hardest. Investors pulled money out of countries that relied on foreign capital, and Morgan Stanley coined the term “Fragile Five” for Brazil, India, Indonesia, South Africa and Turkey. The Indian rupee fell to a record low against the dollar in August 2013. The Fed then surprised markets in September 2013 by holding off on tapering.
The 2013-2014 Taper
When the taper finally came, it was slow and predictable. The steps were roughly as follows:
- December 2013: The Fed announced it would cut purchases from $85 billion to $75 billion a month, starting in January 2014.
- January to September 2014: At most policy meetings, the Fed trimmed purchases by a further $10 billion a month.
- October 2014: The Fed ended net asset purchases, closing the QE3 program.
- 2014 to 2017: The Fed kept its balance sheet steady by reinvesting the proceeds of maturing bonds.
- December 2015: The Fed made its first interest rate increase since 2006, more than a year after purchases ended.
Because the plan was announced clearly in advance, the actual taper caused far less turbulence than the May 2013 hint.
The 2021-2022 Taper
During the COVID-19 pandemic, the Fed restarted large-scale QE in March 2020 and settled at $120 billion a month: $80 billion of Treasuries and $40 billion of mortgage-backed securities. In November 2021, it announced it would cut purchases by $15 billion a month. In December 2021, with inflation rising fast, it doubled the pace to $30 billion a month, and purchases ended in March 2022.
This taper went more smoothly with markets because the Fed had signaled it well in advance. The bigger shock came afterward, from rapid rate hikes and QT, as US consumer price inflation peaked at 9.1% in June 2022.
| Feature | 2013-2014 Taper | 2021-2022 Taper |
|---|---|---|
| Purchases before taper | $85 billion a month (QE3) | $120 billion a month (pandemic QE) |
| Announcement | December 2013 | November 2021 |
| Purchases ended | October 2014 | March 2022 |
| Pace of reduction | About $10 billion per meeting | $15 billion a month, then $30 billion a month |
| Economic backdrop | Slow recovery, low inflation | Strong rebound, high inflation |
| First rate hike | December 2015 | March 2022 |
| Start of balance sheet shrinking (QT) | October 2017 | June 2022 |
| Market reaction | “Taper tantrum” on the first hint in 2013 | Fairly calm; bigger moves came with rate hikes |
Why Is QE Tapering Important?
The Fed’s balance sheet is so large, and the dollar so central to global finance, that even a change in the pace of its buying affects markets around the world. Tapering sends a signal about where the central bank thinks the economy is heading and how soon interest rates may rise. Here are the main channels through which it works.
Interest Rates
The first and fastest effect of tapering is on interest rates, especially long-term ones. QE works like an extra rate cut when the policy rate is already near zero, because heavy bond buying pushes down long-term yields. When the buying slows, that downward pressure fades and yields tend to rise.
The rise is not always dramatic, though. In 2013, long-term yields jumped mainly on expectations. Short-term rates stayed close to zero until December 2015, because tapering slows the growth of money but does not withdraw it.
Inflation
QE adds to the monetary base, so many economists expected it to cause high inflation. In practice, US consumer price inflation stayed mostly below the Fed’s 2% target between 2009 and 2020, partly because much of the new money sat in bank reserves. Critics argue that QE instead inflated asset prices such as stocks and real estate.
Tapering is meant to lean against inflation risks, not to create deflation. In 2021-2022, the Fed sped up its taper precisely because inflation was climbing.
Employment and GDP
Easy money supports borrowing, spending and hiring, which is why QE is linked to stronger GDP growth and job creation. Tapering reduces that support, so in theory it can slow growth and hiring.
A central bank normally tapers only once it believes the economy can stand on its own. In 2014, for example, US GDP kept growing and unemployment kept falling during and after the taper. The risk of a slowdown is real, but it depends on timing and on how quickly rates rise afterward.
Asset Prices
Money supply and asset prices are closely linked. When the Fed buys bonds, it pushes investors into riskier assets such as stocks, corporate bonds and real estate, lifting their prices. When purchases slow, this support fades and asset prices can become more volatile.
Because almost everyone holds these assets in some form, through pensions, homes or savings, changes in their prices shift wealth between groups. That is why tapering decisions are watched so closely.
Impact of QE Tapering on Various Stakeholders
QE affected the lives of people far beyond the United States, and so does its tapering. Some groups gain from it, while others lose. The main stakeholders are described below.
United States Government
The US government runs large budget deficits and borrows by selling Treasury bonds. During QE, the Fed was one of the largest buyers of these bonds, which kept government borrowing costs low. When the Fed tapers, it buys fewer bonds, so other investors must absorb more of the new supply.
If those investors demand higher yields, the government’s interest bill rises. Critics of QE argued that Fed buying made heavy government borrowing too easy. Supporters point out that Treasury demand stayed strong, and that the Fed’s job is to manage the economy, not to fund the government.
United States Taxpayers
Some critics argue that QE quietly taxes anyone holding dollars, because creating new money can reduce the value of existing money. In their view, tapering is a relief for taxpayers and savers. It also tends to lift interest rates on savings accounts, which helps savers who earned almost nothing during QE.
There is another side, however. The Fed earns interest on the bonds it buys and sends its profits to the Treasury, which returned tens of billions of dollars a year to taxpayers during the 2010s. Since 2022, higher interest payments on bank reserves have caused the Fed to run operating losses, so those remittances have stopped for now.
United States Investors
The effects on US investors are uncertain, and forecasts vary widely. The most commonly discussed outcomes include:
- Higher cost of capital: As yields rise, the required rate of return on all investments rises with them, which can weigh on stock and bond prices.
- Lower foreign earnings: Many US companies earn a large share of profits abroad. If tapering strengthens the dollar, those foreign earnings are worth fewer dollars when converted back.
- Repatriation of funds: Higher US yields may pull US capital back home from foreign markets. If many investors sell foreign assets at once, prices fall and the sellers can take losses.
Asset Markets
Asset markets around the world tend to become more volatile when a taper is expected. Prices of almost everything, from real estate to gold, are quoted in fiat money such as the dollar. When the expected supply of that money changes, the prices of everything measured in it can shift.
The result is a redistribution of wealth. Holders of long-term bonds and high-priced growth assets usually lose, while those holding cash or short-term deposits gain from higher yields.
Foreign Investors
Foreign investors who already hold US assets can be on the winning side. Tapering usually strengthens the dollar, as it did in late 2014 and 2015. A foreign investor who converted local currency into dollars earlier gets a currency gain on top of any investment return.
Part of this gain can be offset if the US investments themselves lose value, or if global turmoil hurts business at home. Even so, currency gains have often been the larger effect.
Emerging Markets
Emerging markets attracted large inflows of “hot money” during QE, as investors searched for higher yields than US bonds offered. That capital helped fund growth, but it also left these economies exposed. When tapering makes US assets more attractive, the money can flow out quickly.
The 2013 tantrum showed the pattern: falling currencies, rising borrowing costs and pressure on countries with large current account deficits. Many of these economies have since built bigger foreign exchange reserves, which helped them cope better with the 2021-2022 taper.
| Stakeholder | Likely Effect of Tapering | Why |
|---|---|---|
| US government | Higher borrowing costs | The Fed buys fewer Treasuries, so other buyers may demand higher yields |
| US taxpayers and savers | Mixed; savers gain | Deposit rates rise, but Fed profits sent to the Treasury can shrink |
| US investors | Pressure on returns | Higher discount rates, a stronger dollar and lower foreign earnings |
| Asset markets | More volatility and wealth shifts | Less central bank demand removes a source of price support |
| Foreign investors in US assets | Often gain | A stronger dollar adds currency gains to returns |
| Emerging markets | Capital outflows and weaker currencies | Higher US yields pull back “hot money” that came in during QE |
In short, some groups gain from tapering and others lose, but almost everyone is affected.
What to Watch When a Central Bank Tapers
The two Fed tapers offer clear lessons. Communication matters as much as action: the sharpest market move in 2013 came from a hint, not from actual cuts in buying. A gradual, well-signaled plan, like the 2014 and 2021 schedules, gives markets time to adjust.
Students and investors should also keep the sequence in mind: tapering, then the end of purchases, then rate hikes and finally QT. Each step tightens policy a little more. Watching where the central bank is in that sequence explains much of what happens to bond yields, currencies and stock markets.
Conclusion
Quantitative easing tapering is the gradual slowing of central bank asset purchases. It does not shrink the money supply, but it signals that the era of extra-cheap money is ending. That signal alone can move interest rates, currencies and asset prices around the world.
The 2013-2014 and 2021-2022 episodes show that tapering can be managed smoothly when it is well communicated. They also show that its effects spread far beyond the United States, touching governments, savers, investors and emerging economies alike.
FAQs
What is the difference between QE tapering and quantitative tightening?
Tapering means slowing the pace of new asset purchases, so the central bank’s balance sheet still grows, only more slowly. Quantitative tightening means shrinking the balance sheet by letting bonds mature without replacing them. The Fed tapered from November 2021 to March 2022 and began QT in June 2022.
What was the taper tantrum?
The taper tantrum was the market reaction to Ben Bernanke’s May 2013 hint that the Fed might slow its bond buying. The 10-year Treasury yield rose from about 1.6% to nearly 3% by September 2013, and several emerging market currencies fell sharply.
When did the Fed taper its QE programs?
The Fed announced its first taper in December 2013, began reducing purchases in January 2014, and ended them in October 2014. It tapered pandemic-era QE from November 2021 and ended purchases in March 2022.
Does tapering cause a recession?
Not necessarily. Tapering removes some support from the economy, but central banks usually taper only when growth is strong enough to cope. The US economy kept growing through the 2014 taper.
Why does tapering affect emerging markets so much?
During QE, investors moved money into emerging markets in search of higher yields. Tapering makes US assets more attractive, so that capital can flow back quickly, weakening local currencies and raising borrowing costs.