
The dividend discount model (DDM) values a share as the present value of all the dividends it will pay in the future. The problem is that “all future dividends” means forecasting forever, which is impossible to do year by year.
The Gordon growth model solves this problem. Named after the economist Myron Gordon, it assumes that dividends grow at a constant rate forever, which turns an infinite stream of dividends into one simple formula. It can be used on its own to value mature companies, or as the final step in a more detailed multistage model.
The same logic also allows analysts to split a share’s value into two parts: what the company is worth if it never grows, and what investors are paying for its future growth. That second part is called the present value of growth opportunities (PVGO).
This article explains the Gordon growth model, shows how it fits into a multistage valuation with a worked example, and explains how to use PVGO to judge whether a price is reasonable.
The Gordon Growth Model
The Gordon growth model values a share as a growing perpetuity, a stream of dividends that increases at a constant rate forever:
Where:
- D1 is the dividend expected at the end of the next year.
- r is the rate of return investors require.
- g is the constant rate at which dividends are expected to grow forever.
If you know only this year’s dividend (D0), you can calculate next year’s as D1 = D0 × (1 + g).
A Simple Example
A company has just paid a dividend of 2. Dividends are expected to grow at 5% a year forever, and investors require a return of 10%.
- Next year’s dividend: D1 = 2 × 1.05 = 2.10
- Value = 2.10 ÷ (0.10 − 0.05) = 2.10 ÷ 0.05 = 42
Important Conditions
The model only works when the required return is higher than the growth rate (r > g). If g equals or exceeds r, the formula gives a meaningless result. The growth rate can be negative, which would mean dividends shrinking steadily, but it must always be less than r.
The growth rate must also be realistic for the long term. No company can grow faster than the economy forever, so long-run growth rates are usually set at or below the expected long-term growth rate of the economy.
Using the Gordon Model in a Multistage Valuation
Most companies do not grow at a steady rate from today. They may grow quickly for a few years and then settle down. Analysts handle this by splitting the company’s future into two parts:
- The horizon period: a number of years, often five to ten, for which the analyst forecasts dividends individually.
- The terminal period: all the years after that, when growth is assumed to be stable. The Gordon growth formula is used here to calculate the terminal value.
Worked Example
An analyst forecasts dividends of 4, 5, 6, 7 and 8 over the next five years. After that, dividends are expected to grow at 5% a year forever. Investors require a 12% return.
Step 1: Discount the horizon dividends.
| Year | Dividend | Present value at 12% |
|---|---|---|
| 1 | 4 | 3.57 |
| 2 | 5 | 3.99 |
| 3 | 6 | 4.27 |
| 4 | 7 | 4.45 |
| 5 | 8 | 4.54 |
| Total | 20.82 |
Step 2: Calculate the terminal value at the end of Year 5. The first dividend in the terminal period is Year 6’s: 8 × 1.05 = 8.40.
Terminal value = 8.40 ÷ (0.12 − 0.05) = 8.40 ÷ 0.07 = 120
Step 3: Discount the terminal value to today. 120 ÷ 1.12⁵ = 120 ÷ 1.7623 = 68.09
Step 4: Add them together. Value = 20.82 + 68.09 = 88.91
Two points are worth noticing. First, the terminal value must be discounted back to today; it is a value at the end of Year 5, not now. Second, the terminal value makes up more than three-quarters of the total, which is common. This is why the long-term growth assumption is so important.
Why Assume Growth in the Terminal Period?
An older approach assumed that dividends would stay flat forever after the horizon period, valuing the terminal period as an ordinary, non-growing perpetuity. That is unrealistic: dividends of healthy companies tend to rise over time, at least with inflation. Assuming steady growth is usually more reasonable than assuming growth stops suddenly.
The Present Value of Growth Opportunities (PVGO)
Two Ways to Look at Value
The value of a share can be seen in two ways:
- As the present value of its future dividends, the approach used above.
- As the value the company would have if it never grew, plus the value of its future growth opportunities.
Rearranging this gives:
Finding the No-Growth Value
A company that does not grow pays out all its earnings as dividends and invests nothing new. Its earnings and dividends stay the same every year, forever. That is an ordinary perpetuity, valued as:
Here E1 is next year’s earnings per share. In this special case, earnings and dividends are the same, because everything is paid out.
Worked Example
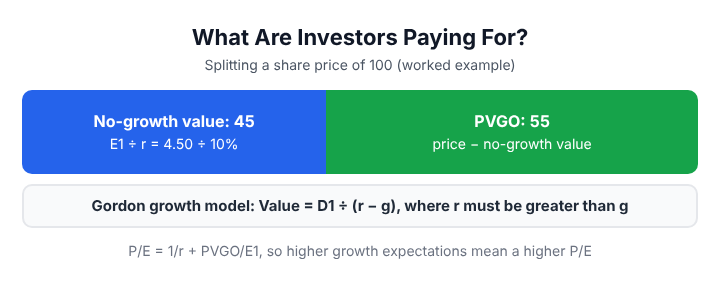
A share trades at 100. Next year’s earnings are expected to be 4.50 per share, and investors require a 10% return.
- No-growth value = 4.50 ÷ 0.10 = 45
- PVGO = 100 − 45 = 55
So 55% of the share price reflects investors’ expectations of future growth. They are paying 45 for the business as it stands today, and 55 for what they believe it will become.
| Part of the value | Amount | Share of price |
|---|---|---|
| No-growth value (E1 ÷ r) | 45 | 45% |
| Present value of growth opportunities | 55 | 55% |
| Share price | 100 | 100% |
Using PVGO in Practice
PVGO is a useful reality check, especially in acquisitions and for highly valued shares.
Suppose a buyer is considering paying 100 for the company above, which already has 60% of its market. The buyer is paying more than twice what the business is worth on its current earnings. To justify that, the company must grow substantially. But with 60% of the market already, it is hard to see how it could double in size unless the whole market is growing quickly and the company keeps a large share of that growth.
If the growth does not look achievable, the price is too high. PVGO forces the analyst to ask: what exactly am I paying for, and is it realistic?
Reading the Market’s Growth Expectations
PVGO can also be used the other way round: instead of judging a price you might pay, you can work out how much growth the market is already expecting.
- Gather three figures: the current share price (P0), next year’s expected earnings per share (E1), usually the analysts’ consensus forecast, and the return shareholders require (r).
- Work out the no-growth value: E1 ÷ r.
- Find the growth share of the price:
Growth share of price = PVGO ÷ Share price
In the example above, it is 55 ÷ 100 = 55%. - Judge how fragile the price is: As a rough guide, when the growth share is low, say below 20%, the price rests mainly on today’s earnings and has some protection. When it is above about 60%, most of the price depends on growth that has not happened yet, and a disappointing forecast can cause a sharp fall.
Keep in mind that the result is sensitive to r. A small change in the required return changes the no-growth value, and therefore PVGO, noticeably.
PVGO and the P/E Ratio
PVGO also explains why some companies trade at high price-to-earnings ratios. Dividing the value formula by earnings gives:
A company with no growth opportunities would trade at a P/E of 1/r, which is 10 when r is 10%. Every point above that reflects the market’s view of its growth prospects. In the example, the P/E is 100 ÷ 4.50, about 22, and roughly 12 of those points come from expected growth.
Conclusion
The Gordon growth model turns an infinite stream of growing dividends into a simple formula: D1 ÷ (r − g). It values mature companies on its own and provides the terminal value in multistage models, where it often accounts for most of a share’s value.
PVGO looks at the same value from another angle, separating what a company is worth today from what investors are paying for its future growth. Used together, these tools help analysts value shares, test their assumptions and judge whether a price makes sense.
Frequently Asked Questions
What is the Gordon growth model?
It is a version of the dividend discount model that values a share by assuming dividends grow at a constant rate forever. The formula is Value = D1 ÷ (r − g).
Why must the required return be higher than the growth rate?
If the growth rate equals or exceeds the required return, the formula produces an infinite or negative value, which is meaningless. A company cannot grow faster than the required return forever.
What is terminal value in the dividend discount model?
It is the value, at the end of the forecast period, of all dividends after that point. It is usually calculated with the Gordon growth formula and must be discounted back to today.
What is PVGO?
PVGO, the present value of growth opportunities, is the part of a share’s value that comes from expected future growth. It equals the share price minus the no-growth value (E1 ÷ r).
How is PVGO related to the P/E ratio?
The P/E ratio can be written as 1/r + PVGO/E1. The higher the share of value that comes from growth opportunities, the higher the P/E ratio.